


0.25 CIP Points


Ask an Expert: From disaster response to prevention
In this edition of Ask an Expert, ARPC's Jason Flannagan explains how turning risk insights into practical resilience measures can reduce future losses and help keep insurance affordable and accessible. Q: What is one key learning from Australia’s experience in...
 21 Sep 2026

 2 mins read
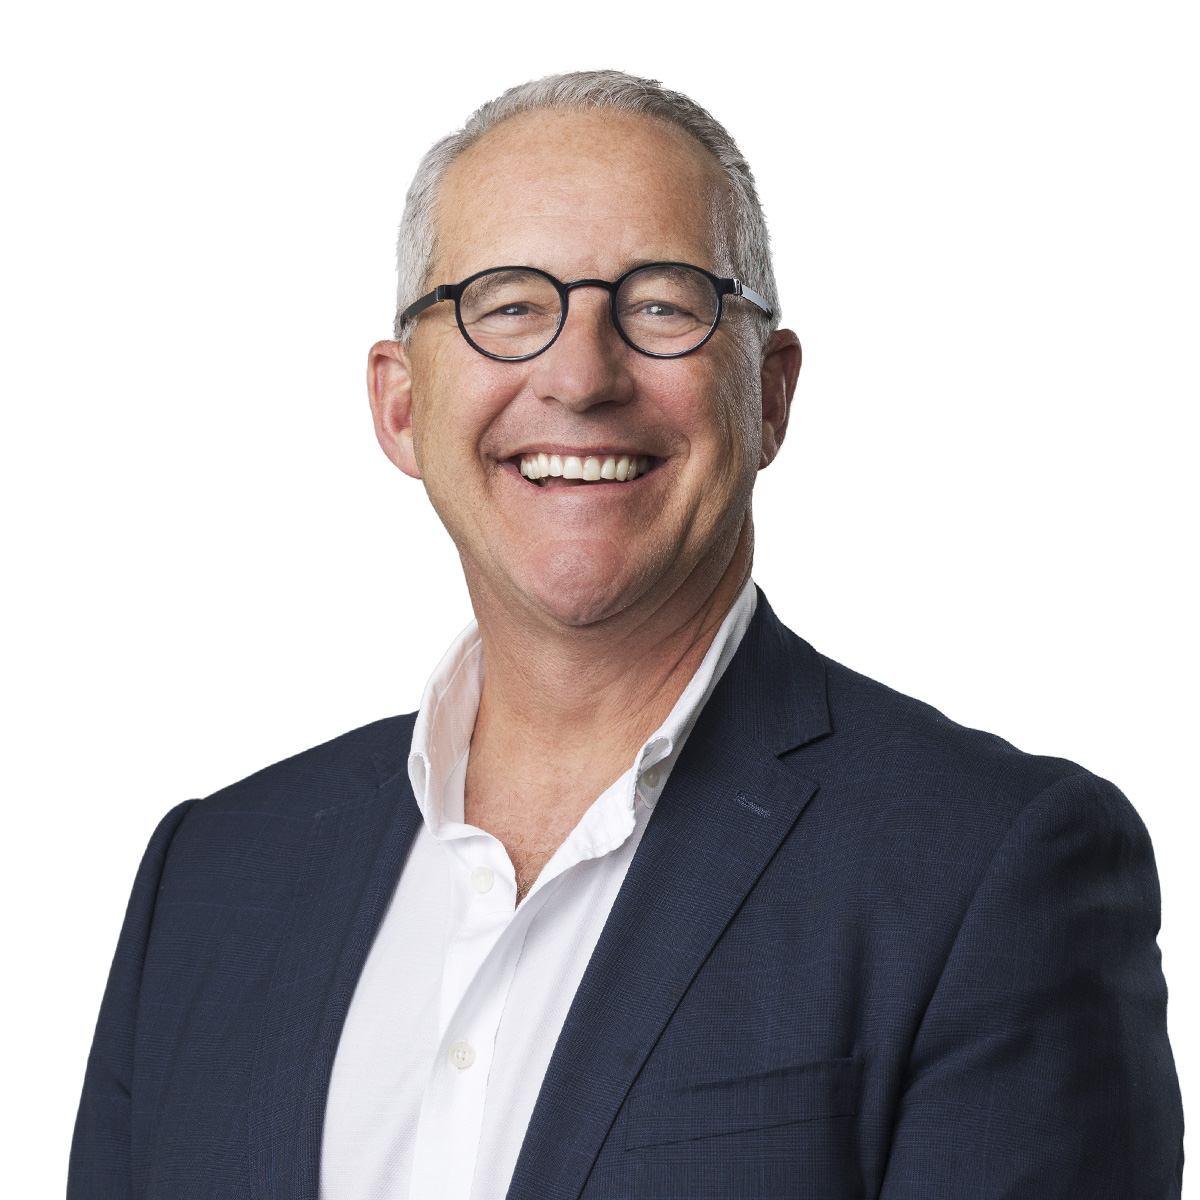
In this edition of Ask an Expert, ARPC’s Jason Flannagan explains how turning risk insights into practical resilience measures can reduce future losses and help keep insurance affordable and accessible.
Q: What is one key learning from Australia’s experience in building resilience to natural disasters?
A: From Jason Flannagan (pictured) – Chief Claims Officer, Australian Reinsurance Pool Corporation (ARPC)
One of the clearest lessons from Australia’s experience is that resilience requires more than responding well after a natural disaster.
We need to turn our understanding of risk into practical action before the next event – reducing future losses and supporting more affordable and accessible insurance over time.
For ARPC, this is closely connected to our experience administering the Cyclone Reinsurance Pool, which was established to improve the affordability and availability of cyclone insurance.
Recent events such as Tropical Cyclone Alfred have provided valuable operational experience, while cyclone pool data is helping us better understand insurance participation, risk and resilience.
Our recent research estimated insurance take-up among flood-risk properties in the regions studied at 65 per cent for buildings and 42 per cent for contents.
For properties at extreme flood risk, this fell to 33 per cent and 23 per cent respectively. These protection gaps highlight the importance of considering risk, affordability and access to insurance together.
Better evidence can also help government and industry understand where mitigation may contribute to improved insurance outcomes.
The pool’s reinsurance pricing recognises eligible measures, including roof upgrades and window protection, through premium discounts.
As at 31 March 2026, $9.4 million in mitigation discounts had been applied to in-force reinsurance premiums. Insurers ultimately determine the premiums offered to their customers.
But financial incentives are only part of the picture. The upfront cost of substantial mitigation, awareness of available measures and understanding of their broader benefits can all influence whether households take action.
Better collection and sharing of mitigation data can also help ensure eligible improvements are recognised in pricing, strengthening the link between investment in resilience and insurance affordability.
ARPC’s first household resilience campaign reached more than half a million homeowners in cyclone-prone regions, connecting practical mitigation actions with potential insurance benefits. The next challenge is to translate awareness into action and continuing to build the evidence about what works.
For the insurance industry, the opportunity is to connect better risk data with customer guidance, recognition of mitigation and opportunities to rebuild more resiliently after a loss. Government, insurers and communities each have a role in making risk reduction achievable.
For ARPC, our contribution is to administer the pool effectively and sustainably, while building evidence and partnerships that support risk reduction and better insurance outcomes.
Ultimately, resilience is not only about helping communities withstand disasters. It is also about reducing the underlying risk that contributes to insurance costs, supporting the longer-term goal of more affordable and accessible cover.
Hear Jason Flannagan speak:
Register for this week’s Thursday Thought Leaders free webinar: Cyclone Risk and Resilience: A Cyclone Pool Update for Industry.
Be in in the room for the panel discussion at Reinsurance Rendezvous: Australia and New Zealand: Shared Lessons in Resilience

0 Comments