



 ArticlesCASE STUDY: What happens when increased costs of working are the deciding factor in a BI claim?

0.25 CIP Points


CASE STUDY: What happens when increased costs of working are the deciding factor in a BI claim?
By Anna Lopata - ANZIIF senior writer After fire destroyed a Malaysian palm oil mill, outsourced production dramatically reduced gross profit losses. This case study examines how mitigation maintained business operations while revealing significant underinsurance of wages. In August 2001,...
 19 Oct 2026

 3 mins read
Summary
Learnings for loss adjusters
• Follow the mitigation story. Establish how alternative operations preserved revenue and what additional costs they created.
• Look beyond year-on-year turnover. Higher revenue than the previous year does not, by itself, rule out a loss against anticipated performance.
• Examine production yields. Alternative processing may sustain operations while producing different financial results.
• Separate expenditure from recoverability. Document mitigation costs and test them against the relevant policy provisions and economic limit.
• Assess each insured item separately. Adequate gross profit cover can coexist with substantial wages underinsurance.
• Check actual savings and workforce decisions. A damaged facility does not necessarily mean payroll costs cease.
By Anna Lopata – ANZIIF senior writer
After fire destroyed a Malaysian palm oil mill, outsourced production dramatically reduced gross profit losses. This case study examines how mitigation maintained business operations while revealing significant underinsurance of wages.
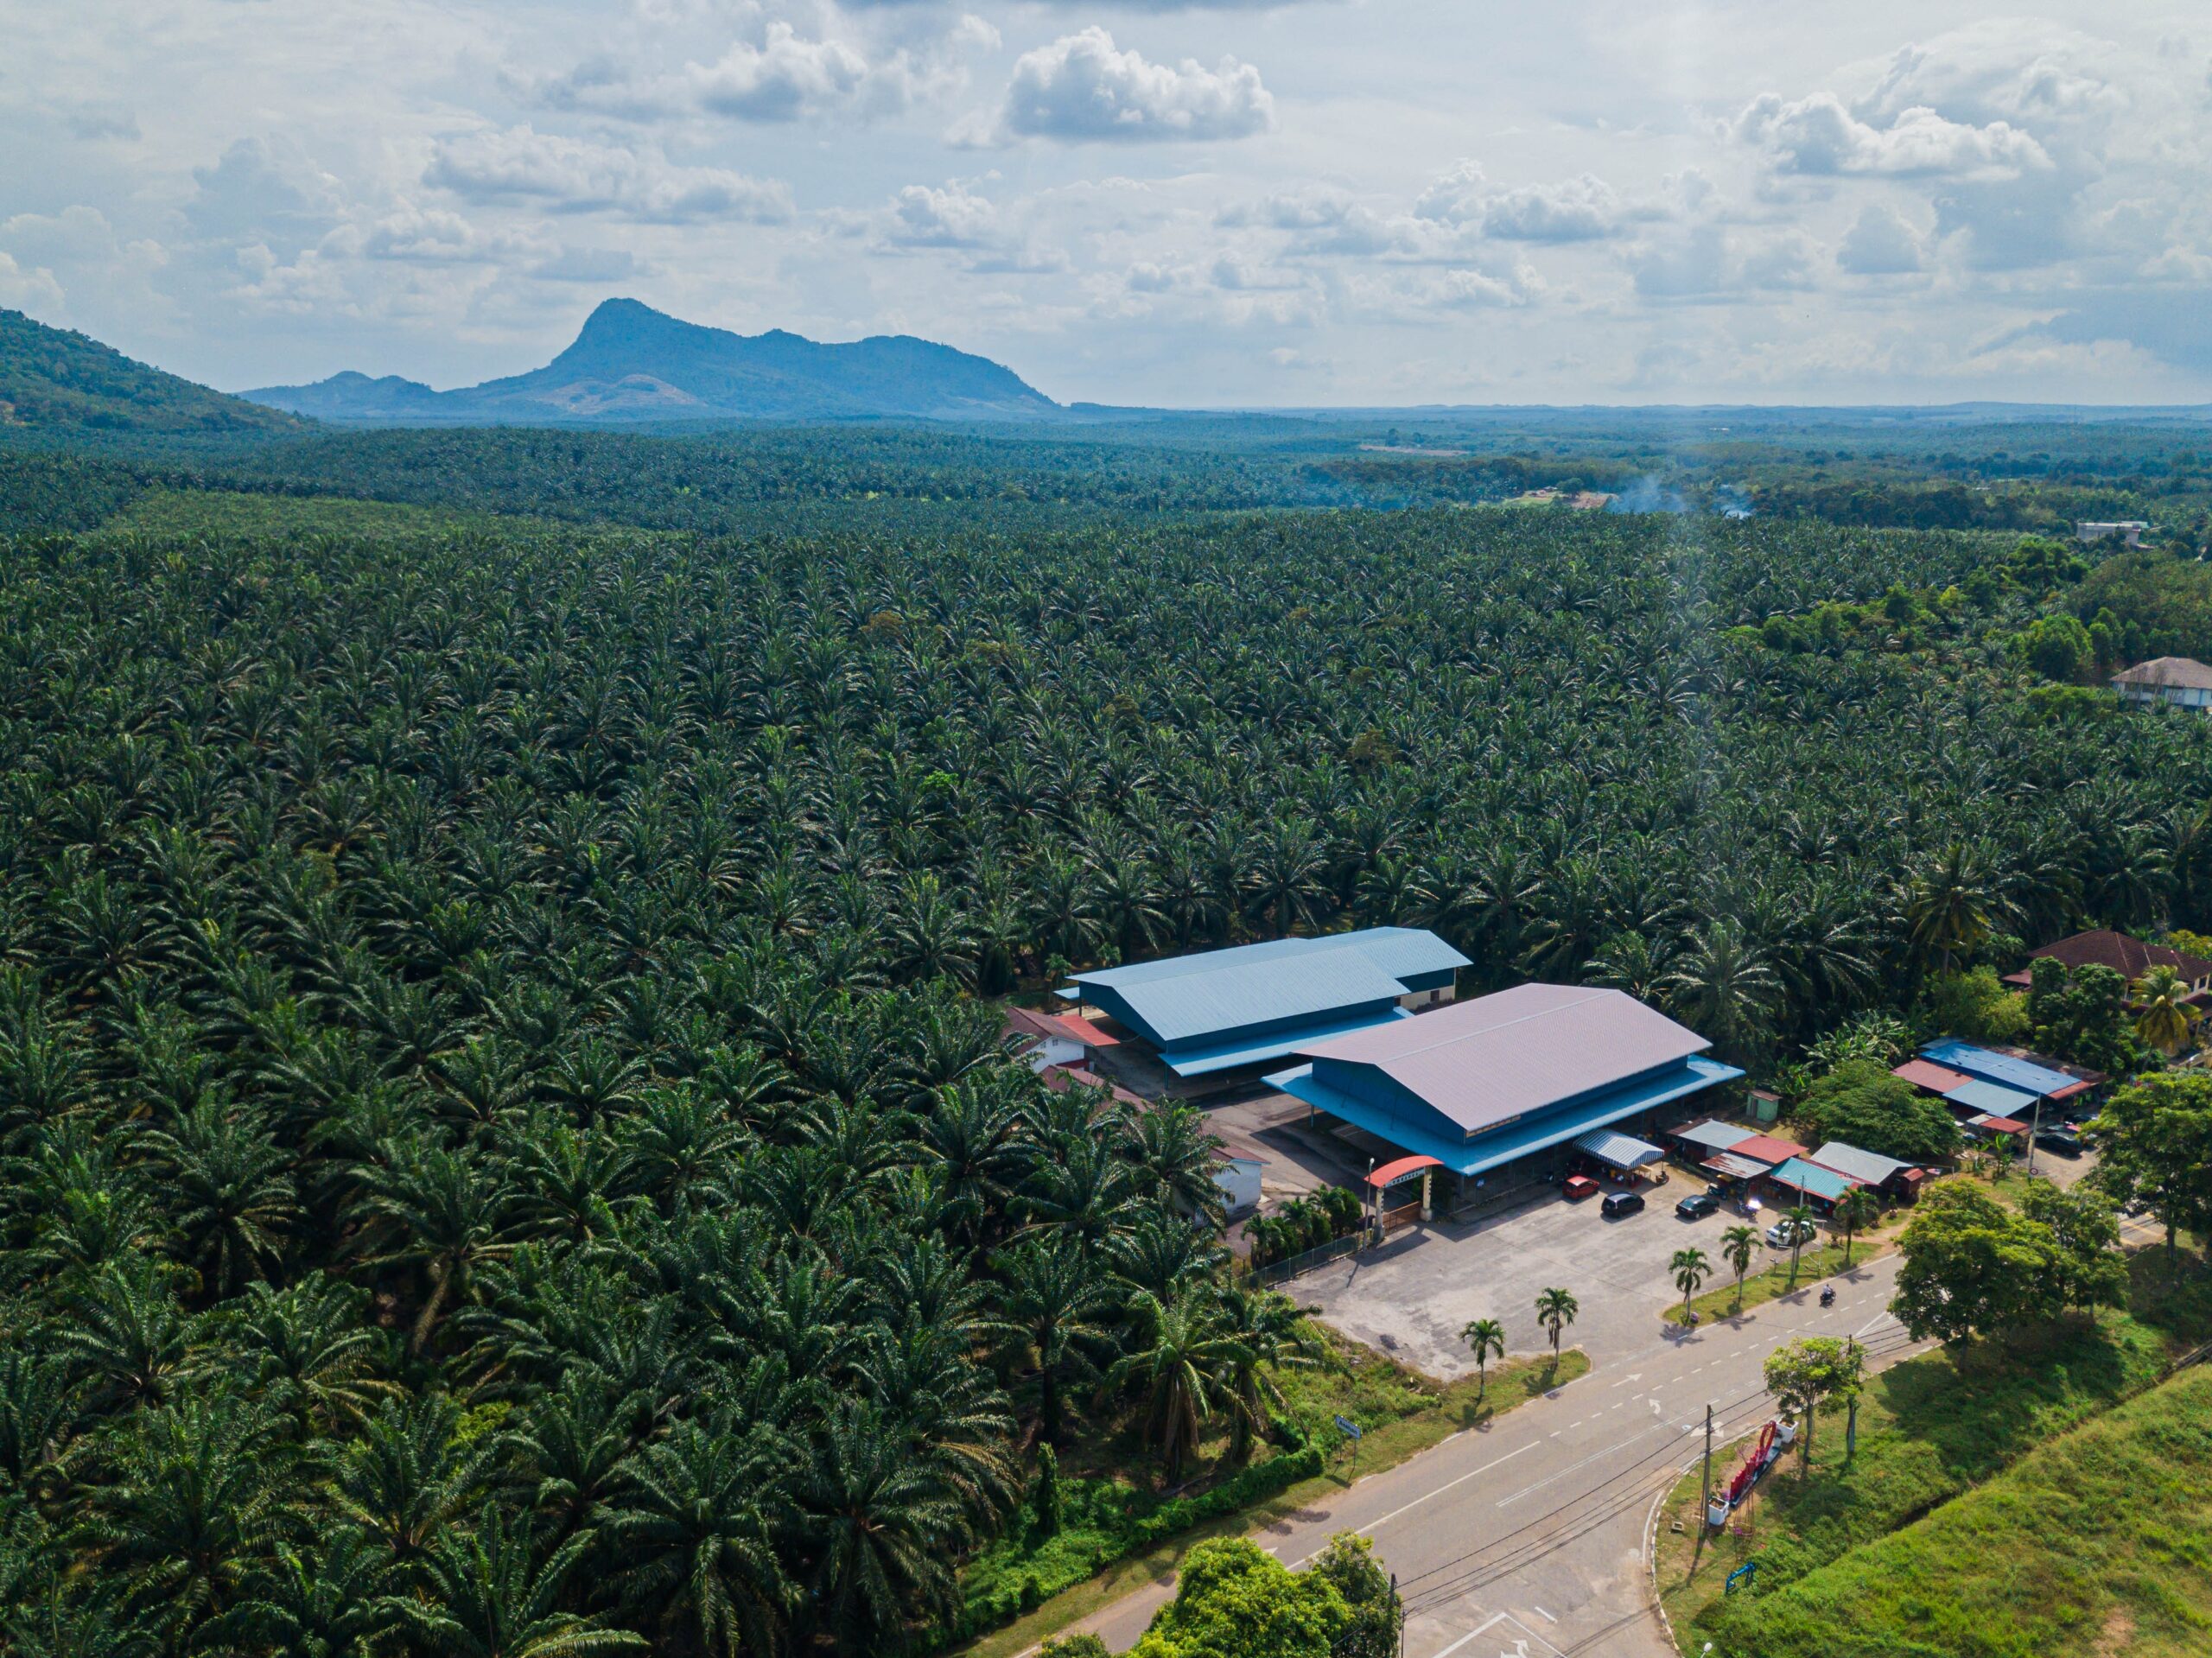
In August 2001, fire gutted a palm oil mill designed to process palm fruit “fresh fruit bunches” (FFB) to crude palm oil (CPO), in rural Malaysia. The premises could no longer process FFB to CPO, and the disruption extended through July 2002.
Yet the loss did not unfold as a straightforward year without production or turnover. The operator transported FFB to other mills for processing to CPO, preserving much of the business that would otherwise have been lost.
That response, approved by the insurer, substantially mitigated the loss. It also produced an unusual claims profile: increased costs of working (ICOW) accounted for most of the assessed business interruption (BI) loss, while the residual loss of gross profit was marginally small.


0 Comments